Walmart MoneyCard®
Green DotFinanceVerified
- 1.87K Reviews
- 3.7
- Downloads
- 500,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
I approached Walmart MoneyCard® as a practical finance app rather than something I would open for entertainment. Its purpose is straightforward: give card users a mobile place to manage money, check activity, and keep an eye on day-to-day spending. That sounds simple, but simplicity matters when the person using the account may be checking it quickly in a supermarket line, sharing household planning with a partner, or helping an older teenager understand where their spending is going.
The app is free, comes from Green Dot, and sits in the finance category. Its store summary promises a better banking experience through a new app, while the short description identifies the Walmart MoneyCard product itself. I found the overall experience most useful when I treated it as the control panel for an existing money routine, not as a replacement for every banking tool a household might need.
How Walmart MoneyCard® fits into a shared household routine
A realistic use case is a household where one person handles the main budget but another person needs visibility into available money or recent card activity. In that situation, a mobile account view can reduce the need to pass around paper receipts or repeatedly ask someone else to check the balance. I would use the app before a grocery trip, after a fuel purchase, and again when reviewing the week’s spending. Those small checks are more useful than opening it only when something has gone wrong.
Shared use needs a clear boundary, though. I would not treat the app as a communal dashboard that everyone in the home should freely access from one unlocked phone. A finance app contains personal information, and convenience can quickly become a privacy problem if household members use the same device profile or leave the account open. The better arrangement is for the account holder to manage access directly and show relevant information when coordination is needed.
This distinction is especially important for couples or relatives who divide responsibilities. One person might handle regular purchases while another tracks the overall household budget. The app can support a conversation about the current balance and recent activity, but I would still keep a separate shared budgeting habit—perhaps a simple note or spreadsheet—if several people need to plan together. A card-management app and a household budgeting system solve related but different problems.
My practical advice is to decide in advance what the app is for. If it is mainly for checking available funds, keep that task quick and consistent. If it is being used to investigate a purchase, review the activity carefully rather than relying on memory. If it is part of a teenager’s money education, let the adult explain the account boundaries before handing over a phone. Clear ownership is more valuable than casual shared access in a finance app.
What I would do before handing over a phone
On a shared device, I would first confirm whose account is signed in and whether the phone is protected by a proper screen lock. I would also avoid leaving the app open while passing the device to someone else. These are ordinary precautions, but they matter more for financial software than they do for a weather or recipe app.
Other Stories to Read




I would then agree on what the other person actually needs to know. A partner may need the current balance for a planned purchase, while a young person may need help interpreting a transaction. Showing only the necessary screen or explaining the result verbally can be safer than giving unrestricted access. This approach also prevents a common household mistake: confusing cooperation with shared credentials.
Another useful habit is to check activity soon after a purchase rather than waiting until the end of the month. That makes it easier to recognize familiar spending and notice something that needs attention. It also gives families a chance to discuss timing. A purchase may appear later than expected, and a person who assumes that every transaction updates instantly could make an inaccurate decision about what money remains available.
I would not use the app as the only record for a complicated household. For recurring bills, reimbursements, cash spending, and purchases made by several people, a second record is still sensible. The Walmart MoneyCard app can help one person see the card account, but it does not automatically become a complete family ledger just because more than one person relies on the same balance.
Setup is less about speed than account boundaries
The initial setup should be approached as an account-ownership task, not as a casual app installation. Before signing in, I would make sure the correct person is using the correct device and that the account information is not being entered while someone unnecessary is watching. This is particularly important in a home where phones are borrowed, tablets are shared, or a parent regularly helps a child with technology.
I also recommend keeping the app’s role separate from the role of a general banking app. A typical bank application may bring checking, savings, transfers, deposits, and other services into one place. Walmart MoneyCard is more focused around its own card relationship. That focus can make it easier to find the information relevant to the card, but it can also feel limited if you expect one application to organize every account in your financial life.
The Android requirements are relatively approachable: the app supports Android version 9 and later. That makes it a realistic option for people who do not replace phones frequently, although a compatible operating system does not guarantee that every older handset will feel equally smooth. I would still install it on the device used most reliably for financial tasks, rather than automatically choosing the oldest shared phone in the household.
The current version is 2.7.0. For a finance app, I consider updates part of the setup routine rather than an optional extra. Keeping the app current can reduce avoidable compatibility problems, but I would also avoid updating immediately before an important payment or trip if the phone is already unstable. My preference is to update during a calm moment, sign in afterward, and confirm that the account view is available before relying on it.
One trade-off is that a dedicated card app may be easier to understand than a broad banking platform, especially for someone who only needs card-related information. On the other hand, a household that already uses a main bank, a budgeting service, and a payment wallet may find another login adds mental overhead. I would choose this app when the Walmart MoneyCard is central to the routine, not simply because it is free.
Coordinating purchases without turning the app into a family control system
In my experience, the most useful household workflow is simple: one person checks the account, communicates the amount available for a planned purchase, and the buyer keeps the receipt until the transaction is easy to identify. That process works for groceries, school supplies, or a shared fuel budget. It does not require everyone to have permanent access to the account, and it reduces the chance that two people spend against the same money without realizing it.
The app is also useful for a quick pre-purchase check. Before a large household expense, I would look at the current account position and recent activity, then compare that with the amount needed for the purchase. I would not treat the displayed balance as a promise that every future expense is covered. Pending activity, automatic obligations, and purchases made by another person can change the practical amount available.
That is one of the less obvious trade-offs of shared use: visibility is not the same as coordination. Two people can look at the same account and still have different assumptions about what the money is reserved for. The app can show account information, but the household still needs a spoken or written agreement about priorities. I would create a short list of upcoming essentials and update it whenever someone makes an unplanned purchase.
For reimbursements, I would keep the process equally clear. If one person buys something for the home, record the purpose and amount outside the app so that the transaction has context later. A card activity screen may help identify the payment, but it will not replace a note explaining whether the purchase was groceries, a gift, or an item bought for one specific family member.
This is where the app compares differently with a full budgeting service. A budgeting tool may be better for categories, goals, and a broader view across accounts. A standard bank app may be better for people who want all their banking relationships together. Walmart MoneyCard is more appealing when the priority is a direct, focused way to stay connected to this particular card. I would not expect it to provide the same household planning depth as a dedicated budget platform.
Age, trust, and the right level of independence
The content rating is Mature 17+, which is an important part of deciding how the app fits into a family. I would not interpret that label as a substitute for an adult’s judgment about financial responsibility, but I would take it seriously when deciding whether a younger person should use the app independently. A teenager may be ready to learn about spending without being ready to manage account access alone.
For an older teenager, I would begin with guided use. We could review the balance together, identify a recent purchase, and discuss why the available amount is not the same thing as permission to spend everything. I would avoid turning the exercise into surveillance. The goal should be understanding, not creating a situation where the young person feels that every ordinary purchase is being watched without explanation.
For a younger child, I would keep the app in the adult’s hands and teach the money lesson away from the account screen. A child can learn to compare a purchase with a spending limit without seeing private financial details. This separation is useful because it preserves the adult’s account boundary while still making the financial routine understandable.
Trust also works in the other direction. If an adult family member needs help with the app, I would assist with navigation but let the account holder remain present for sign-in and sensitive decisions. Writing down passwords or saving them in a place everyone can reach may feel convenient, but it weakens the boundary that protects the account. The safest household arrangement is one where assistance does not quietly become control.
People who need formal shared ownership, multiple users with distinct permissions, or detailed supervision should examine whether a focused card app meets that need before committing to it. I would not assume that a household can reproduce the controls of a family banking product simply by sharing one device. If account roles are central to your situation, a service designed around those roles may be a better fit.
How the app feels for everyday money checks
For ordinary use, I prefer a finance app that lets me answer one question quickly: what is happening with this card right now? Walmart MoneyCard is strongest when I use it that way. I can build a habit around checking before spending, reviewing activity after spending, and discussing unusual transactions while the details are still fresh.
The free price removes one barrier for people who want to try the app without adding another subscription to the household budget. That does not make it automatically the right choice. A free app can still cost time if it duplicates tools already available elsewhere, and a household may value consolidation more than a separate card-focused experience.
The store presence shows an average rating of 3.7 from around 3.7 thousand ratings, with roughly 1.9 thousand written reviews and more than 500 thousand installs. I see those figures as signs that the app has meaningful real-world use, but not as proof that every household will have the same experience. Finance apps are judged heavily by login reliability, transaction timing, device behavior, and individual account circumstances, so I would pay more attention to whether its workflow matches your needs than to the score alone.
The release date is March 12, 2025, which places the app in a relatively recent stage of its life. That can be encouraging if you prefer a newer interface, but it also makes me cautious about building an elaborate household process around it immediately. I would first use it for routine checks, learn how activity appears in practice, and keep another way to access essential account information during the adjustment period.
Where it is a good fit—and where I would choose something else
I would recommend Walmart MoneyCard to someone whose daily money routine revolves around the Walmart MoneyCard and who wants a direct mobile view of that relationship. It is also a reasonable choice for a household that needs one accountable cardholder to coordinate spending with others without turning every family member into an account user.
I would be more hesitant for someone who wants a complete financial command center. If you regularly move between several bank accounts, track shared bills, manage savings goals, or need detailed category reports, a broader banking or budgeting application may save effort. Adding this app may still be useful for card-specific checks, but it should not be mistaken for a replacement for those other tools.
I would also skip it as a shared-device solution if the household cannot maintain basic privacy. A phone that is constantly passed between people, has no dependable screen lock, or is used by several account holders creates unnecessary risk. In that case, the problem is not that the app is unsuitable for finance; it is that a shared access pattern is unsuitable for a personal financial account.
Another situation where I would look elsewhere is formal family management. If you need separate permissions, clearly divided responsibilities, or a structured way to supervise several users, choose a product whose account design explicitly supports that arrangement. I would not improvise those boundaries by exchanging login details or leaving an account signed in for convenience.
My household verdict after using it as a card companion
Walmart MoneyCard works best when I keep its purpose narrow and practical. It gives the cardholder a mobile way to stay aware of the account, and that can make household coordination easier when one person remains responsible for access. The strongest routine is not “everyone opens the app whenever they want”; it is “the right person checks the account, communicates clearly, and records the context of shared spending.”
Its limitations become clearer when the household expects more. It is not the same as a full budgeting workspace, a multi-user family dashboard, or a substitute for careful communication. The Mature 17+ context also means I would introduce it thoughtfully to younger family members, using guided learning rather than casual access.
Overall, I would recommend it to a Walmart MoneyCard holder who wants a focused, free finance app and values quick account awareness over a large collection of budgeting tools. I would keep a separate household spending note for shared purchases and avoid treating one signed-in phone as a family account. Used within those boundaries, it is a sensible card companion; used as an all-purpose household finance system, it is a less convincing choice.
Highlights
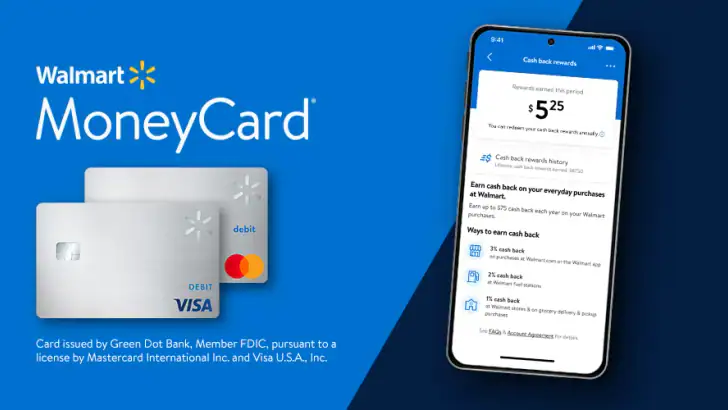
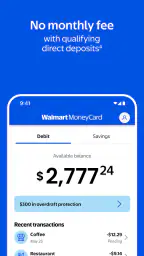
- No monthly fee when you receive qualifying direct deposits.
- Mobile check deposit lets you add funds without visiting a store.
- Early direct deposit may make eligible paychecks available sooner.
- Customizable transaction alerts help you monitor account activity.
- Card can be used for purchases and ATM withdrawals where accepted.
Limitations
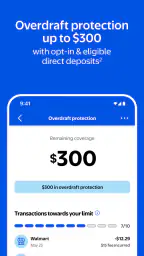
- Monthly fees may apply if direct-deposit requirements are not met.
- ATM withdrawals outside the network can include additional charges.
- Cash reload fees and participating locations vary by retailer.
- Some features and fees may differ depending on your account type.
- Not a traditional bank account and may lack broader banking services.
Frequently Asked Questions
01What is Walmart MoneyCard® and how does it work?
Walmart MoneyCard® is a prepaid debit card and mobile account designed for everyday spending, direct deposit, bill payments, money transfers, and cash management. You generally spend only the funds loaded onto the account, so it is not a traditional credit card and does not provide a revolving credit line. Availability, features, fees, and account requirements may vary by state and product terms.
02Do I need a bank account or credit check to use Walmart MoneyCard®?
You do not normally need a traditional bank account or a credit check to apply for a Walmart MoneyCard® account. However, registration requires personal information, and identity verification may be requested to comply with financial regulations. Some features, transaction limits, or services may only become available after verification. Review the current cardholder agreement before relying on the account for important payments.
03What fees should I know about before downloading or using the app?
Walmart MoneyCard® may involve fees depending on how you use the account. Possible charges can include a monthly plan fee, fees for certain cash reloads, ATM withdrawals, expedited services, or other transactions. Some fees may be reduced or waived when you meet qualifying conditions, such as receiving eligible direct deposits. Always check the latest fee schedule in the app or official terms.
04Can I deposit my paycheck or government benefits directly to Walmart MoneyCard®?
Yes, eligible users may be able to receive paychecks, government benefits, tax refunds, or other qualifying payments through direct deposit. The app and account information can help you locate the details needed to set up the deposit with your employer or benefits provider. Posting times depend on the payer, banking procedures, weekends, and holidays, so early availability should not be guaranteed.
05Is Walmart MoneyCard® safe, and what should I do if my card is lost?
Walmart MoneyCard® includes account security tools such as login protection, transaction monitoring, and the ability to manage or lock a card through the app, although no financial service is completely risk-free. If your card is lost, stolen, or used without permission, lock it immediately, review recent transactions, and contact official customer support. Never share passwords, verification codes, or full card details with unsolicited callers.


